US business banking for international founders: what peers gather first
What international founders at IFN tend to gather before they walk into a US business banking conversation, at overview level.
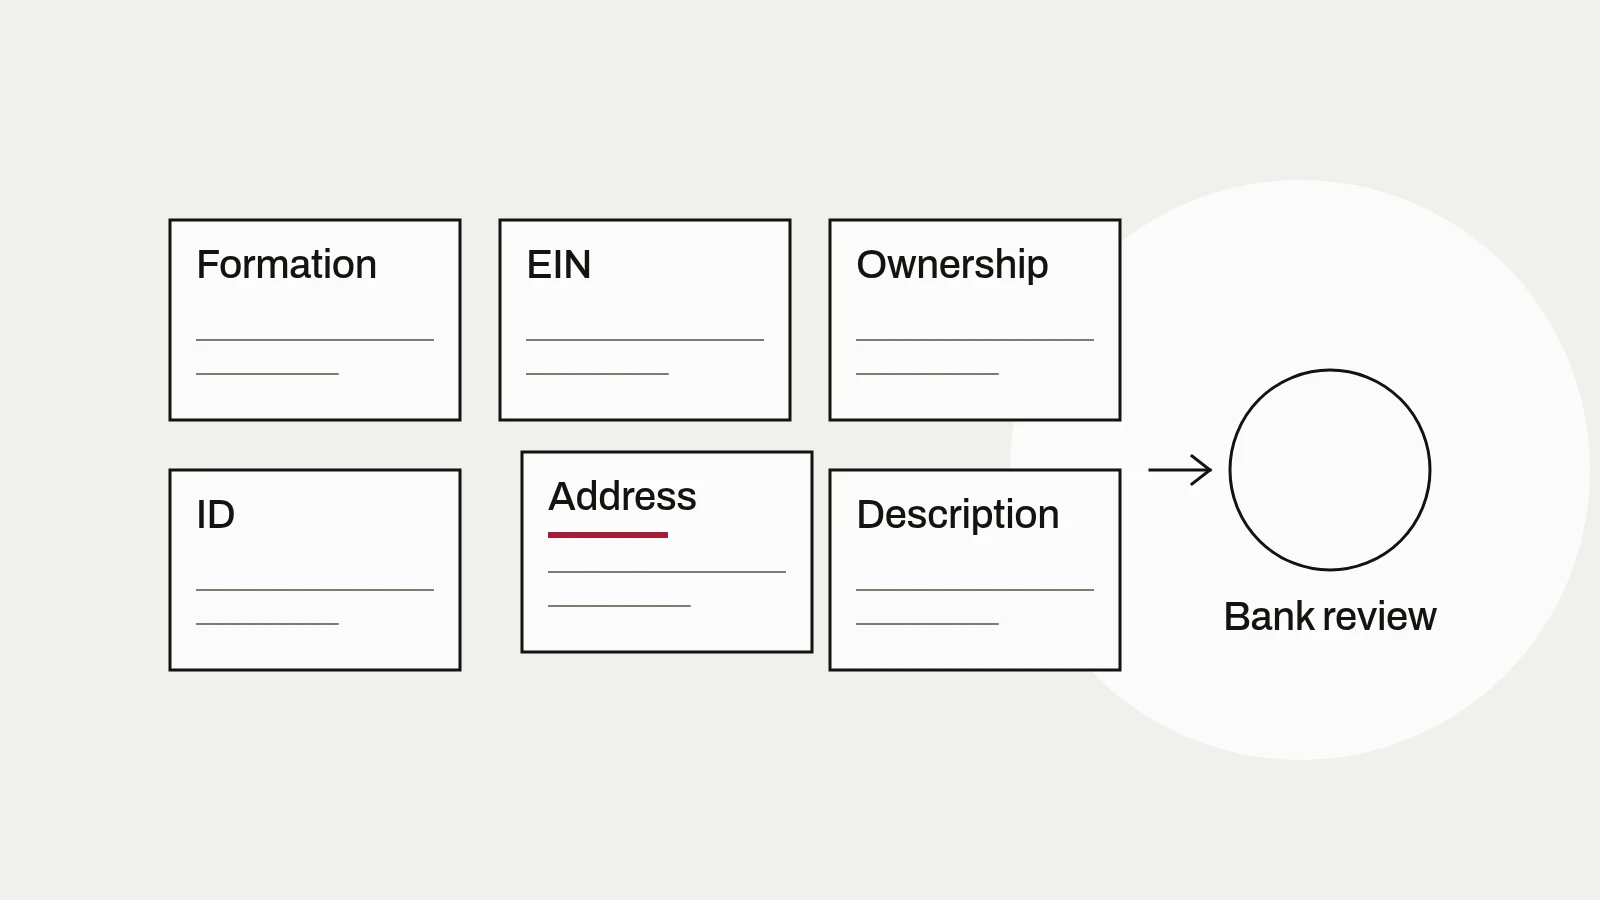
After formation and EIN talk, banking is the next wall at IFN Austin meetups. Founders often say they assumed the hard part was "being foreign." What they describe afterward sounds more like incomplete company paper: mismatched names, a registered-agent address used as the operating address, missing EIN confirmation, or ownership docs that do not match passport spellings.
This is peer orientation on what people tend to gather before they walk into a bank or remote onboarding flow. It is not a downloadable checklist, not a promise any bank will approve you, and not product endorsement. The fuller pack language belongs with membership and Resources.
Disclaimer
This is not banking, legal, tax, or immigration advice. Bank and fintech policies change. Underwriting is individual. Verify requirements with the institution you apply to. IFN shares patterns from founder conversations, not guarantees.
The wrong wall, in meetup language
A common story in the room: form a US LLC or C-corp from abroad, upload a passport and Articles PDF to a remote business account, get stalled or declined, then conclude "US banks do not want internationals."
Peers who cleared remote onboarding usually rewrite that story: the underwriter could not reconcile an incomplete company file. Nationality still matters for some products. Incomplete paper fails more often than founders expect.
Industry examples (not IFN endorsements): Mercury's How to open a U.S. bank account remotely and OtoCo's 2026 foreign-owned LLC banking guide. Your bank's checklist still wins.
What peers tend to gather (overview, not a pack)
Every institution differs. At a high level, founders who later cleared onboarding usually had these categories ready before they applied:
- Formation evidence with the exact legal name, state, and filing date. Entity choice and sequencing are a separate peer conversation; keep company paper frozen before you apply.
- EIN confirmation that matches that legal name. IRS EIN overview and Form SS-4 instructions.
- Ownership and signing authority clear enough that beneficial owners and control persons are not a mid-review surprise.
- Government IDs for owners and control persons, with names that match formation docs.
- A real business mailing or principal place of business address, separate from the registered agent used only for service of process. Many remote underwriters reject registered-agent-only or PO box-only addresses. Check yours.
- A boring, true business description. Vague activity language creates manual review. Inventing a safer-sounding industry creates a worse problem later.
That is orientation, not a fillable inventory. The item-by-item pack and member-channel walkthroughs live deeper in Resources and with membership.
Remote path vs traditional path
Remote path: browser upload plus review. Peers report stalls when the address is the registered agent, the EIN name mismatches, beneficial ownership is incomplete, or the activity is unsupported.
Traditional path: denser KYC, longer timelines, sometimes an in-person step. Branch visits with Articles alone often burn the trip.
Product names come and go. Re-read current eligibility pages, including any prohibited-residence list, before you build plans on a forum thread.
SSN, ITIN, and a separate visa track
In many remote stories, the company is the customer and controlling persons provide passport KYC. An SSN is not always required for the company account. An ITIN is personal; it is not a substitute for the company's EIN. Some banks still want a US person with signing authority.
Visa status is a separate track. Owning a US company is not permission to work in the United States. Keep personal status questions for immigration counsel, not for the banking underwriter.
When we stop talking
Call a professional or the bank's support channel when:
- You need a product recommendation for your facts
- Your industry or residence may be unsupported
- Names or addresses already conflict across docs
- Someone suggests misstating activity to pass review
- Tax residency or payroll setup enters the chat
- A decline letter needs interpretation against your KYC file
Meetup peers can share what they assembled. They cannot underwrite you.
Soft next steps
Bring your banking-prep questions (not your passport data) to the next IFN meetup. Guests are welcome; register on Luma or check ifn.community. For the private member channel, members-only call, and the fuller banking pack / teaser PDF language as it ships, Become a member or browse Resources.
Sources
- Mercury, How to open a U.S. bank account remotely
- OtoCo, How to Open a US Bank Account for a Foreign-Owned LLC (2026 Guide)
- IRS, Employer identification number
- IRS, Instructions for Form SS-4